12 Nov What Insurance Do I Need to Build an Extension?
Quick Answer: Building an extension involves risks that your regular home insurance policy may not fully protect against. Depending on the scale of the project, you may need additional cover for structural damage, construction materials and unexpected incidents on site. It’s also important to establish which risks are covered by your builder’s insurance and which remain your responsibility. Reviewing these arrangements before construction starts can help prevent costly gaps in protection.
If you’re planning a house extension, you may need more than your existing home insurance to protect your property during construction. Depending on the project, you could need specialist renovation insurance, contract works cover and confirmation that your builder has appropriate liability insurance.
Before building an extension, contact your home insurance provider, explain the proposed work and confirm what is covered in writing. This helps protect your home, belongings and investment before construction begins.
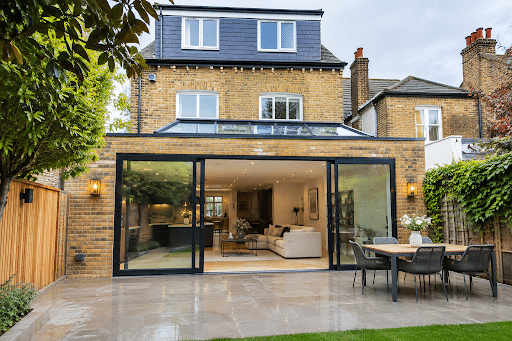
Whether you’re planning a kitchen extension in West London or a larger double-storey extension in South London, understanding your insurance responsibilities can help you avoid unexpected costs and disputes.
Does Home Insurance Cover Building an Extension?
Standard home insurance does not automatically cover all the risks associated with building an extension. Your existing policy may continue to protect certain parts of your home, but damage caused by construction work, structural alterations or exposed building elements may be excluded.
Your insurer may also change your policy conditions while the work takes place.
For example, removing an external wall to connect a new kitchen extension to your existing house could expose the property to rain, theft or accidental damage.
Even if your home insurance includes accidental damage cover, it does not necessarily protect against construction-related incidents.
Do I Need to Tell My Home Insurance Provider About Building Work?
Yes. You should tell your home insurance provider about a planned extension before construction starts.
Your insurer will usually want to know:
- The type and size of the proposed extension
- Whether structural walls or roofing will be altered
- The estimated construction cost
- The expected start date and project duration
- Whether you will remain living in the property
- Whether scaffolding or temporary roof coverings will be required
- Who will carry out the building work
Your insurance company can then confirm whether your existing home insurance remains suitable, whether restrictions apply or whether specialist cover is necessary.
Failing to disclose significant building work could affect future claims or the validity of your policy.
What Types of Insurance Do You Need for a House Extension?
The main types of insurance to consider are buildings insurance, specialist renovation insurance, contract works insurance and appropriate contractor liability cover. The right combination depends on the extension’s complexity, the construction contract and which party is responsible for insuring the existing property and new works.
Buildings and Contents Insurance
Buildings insurance protects your existing home’s structure against specified insured risks, such as fire and storm damage.
Contents insurance protects eligible personal belongings, although restrictions may apply during renovations.
Before construction, check whether your policy covers accidental damage to the existing structure and belongings while builders are working.
Renovation and Extension Insurance
Specialist renovation insurance is designed for properties undergoing building work.
Depending on the policy, it may provide protection for:
- The existing building
- Structural alterations
- Fire, storm and flood damage
- Theft of insured building materials
- Accidental damage during construction
- Unfinished building works
- Specified unoccupied-property risks
Some policies can also include alternative accommodation following an insured incident that makes the home uninhabitable.
Check the exclusions carefully, particularly for water ingress, defective workmanship, temporary structures and existing-property damage.
Contract Works Insurance
Contract works insurance, sometimes called contractors’ all risks insurance, can cover insured construction work and materials during the building process.
For example, if an insured event damages a partially completed extension, the policy may cover the cost of replacing affected materials or rebuilding damaged work.
However, contract works insurance does not automatically insure the existing house.
You should establish whether the homeowner, contractor or both parties need to be named on the relevant policies.
What Insurance Should Your Builder Have?
Your builder should have insurance appropriate to the work being undertaken, particularly public liability insurance and, where legally required, employers’ liability insurance. Contract works insurance may also be needed, depending on the agreement and who carries the risk for materials and construction work.
Before hiring a building contractor, request current insurance documentation rather than relying solely on assurances that the company is fully insured.
Public Liability Insurance
Builder’s public liability insurance can protect against covered claims involving injury to third parties or damage to third-party property caused by the contractor’s activities.
For example, construction work might accidentally damage a neighbour’s garden wall or a contractor might cause an injury to a visitor.
Public liability insurance is not generally a substitute for insurance protecting your own building and the works themselves. Policy exclusions, liability requirements and coverage limits still apply.
Employers’ Liability Insurance
Employers’ liability insurance protects businesses against covered employee injury or illness claims.
In Great Britain, employers generally need at least £5 million of employers’ liability cover from an authorised insurer, subject to statutory exceptions.
Homeowners should check that their contractor has the necessary cover for their workforce, including how subcontractors are insured.
Contractors’ All Risks Insurance
A contractor may hold an all risks policy that includes contract works and liability sections.
Ask whether it covers your particular extension, the full contract value and materials stored on site.
You should also confirm the policy’s start and end dates and whether specialist activities, such as excavation or structural alterations, are excluded.
What Does Building Extension Insurance Actually Cover?
Building extension insurance can cover specified losses affecting construction work, materials or the existing property, depending on the policy. Common insured events may include fire, theft, storm damage and certain accidental damage. However, exclusions, excesses and coverage limits determine whether an individual claim will be paid.
Consider three examples.
Fire during construction: A fire damages part of the unfinished extension and spreads into the existing kitchen. Contract works cover may respond to the new work, while the existing building requires suitable buildings or renovation insurance.
Theft of materials: Insured materials are stolen from a building site. A contract works policy may provide compensation, provided its storage and security conditions have been met.
Water damage: Rain enters through an unfinished roof opening and damages internal decorations. Whether this is covered depends on the policy’s provisions for temporary weatherproofing, water ingress and building works.
These examples illustrate why checking the policy wording matters more than simply knowing the insurance product’s name.
Do Different Types of House Extensions Need Different Insurance?
Different extension projects can require different insurance arrangements because construction risks vary with size, structural complexity, excavation depth and the condition of the existing property.
Single-Storey and Kitchen Extensions
A single-storey rear extension may involve new foundations, roofing and opening an external wall.
A kitchen extension can also involve plumbing, electrical installations, fitted cabinetry and expensive appliances.
Ask whether your insurance covers the existing kitchen, new construction materials and any temporary exposure during the works.
Double-Storey Extensions
A double-storey extension may require more extensive structural alterations, scaffolding and temporary weather protection.
These factors can increase the insured value and complexity of the project.
Your insurer may request additional information about the building method, structural design and contractor.
Side Return and Basement Extensions
Side return extensions are common in London terraced properties, where construction may take place close to neighbouring buildings.
Basement extensions can involve excavation, underpinning and additional structural risks.
For these projects, discuss neighbouring-property exposure, ground movement, excavation exclusions and any specialist insurance requirements with your insurer or broker.
Who Pays if Building Work Damages a Neighbour’s Property?
Responsibility for damage to a neighbouring property depends on what caused the damage, the parties’ legal responsibilities and the applicable insurance policies.
A builder’s public liability policy may respond where the contractor is legally liable for insured damage. However, damage arising from excavation, vibration or structural movement may involve exclusions or additional insurance requirements.
For example, if excavation near a neighbouring house causes cracking, the circumstances must be investigated to establish responsibility and available cover.
Do You Need a Party Wall Agreement?
Certain extension works near shared walls, boundaries or neighbouring foundations fall under the Party Wall etc. Act 1996.
Depending on the work, you may need to notify adjoining owners and follow the statutory procedure before construction begins.
A party wall agreement or award does not replace building insurance or automatically provide compensation cover.
For higher-risk projects, ask your surveyor and insurance adviser whether additional neighbouring-property protection, including non-negligence insurance, should be considered.
How Much Does Insurance for a House Extension Cost?
The cost of extension insurance depends on the construction value, property characteristics, project duration and risks involved. There is no reliable fixed premium that applies to every house extension, so homeowners should obtain quotations based on their specific plans.
Factors that may influence the cost include:
- Size and condition: A larger extension or an older property with structural vulnerabilities may present greater risks.
- Extent of refurbishment: Combining an extension with extensive renovations increases the scope of insured works.
- Structural changes: Removing load-bearing walls, excavating foundations or altering roofing can affect the premium.
- Specification: High-value glazing, kitchens, bathrooms and bespoke joinery may increase the insured value.
- Plumbing and electrics: Extensive alterations can introduce additional construction risks.
- Project management and duration: Longer projects, multiple contractors and complex arrangements may affect underwriting.
- Unforeseen work: Hidden structural defects or changes to the building programme may require policy adjustments.
Decoration and final finishes should also be included when calculating the value of works requiring cover.
Request quotations from your existing insurer and, where appropriate, a specialist renovation insurance broker.
Compare the total premium, excesses, exclusions and coverage limits rather than choosing solely on price.
What Should You Check Before Building an Extension?
Before construction begins, confirm that the existing house, new building works and relevant third-party liabilities have suitable insurance arrangements. The policies should reflect the actual scope of work and the responsibilities agreed between you and your contractor.
Follow this checklist:
- Notify your home insurer. Provide the proposed plans, estimated cost and construction programme.
- Confirm existing-property cover. Ask whether the building and contents remain insured during structural work.
- Review your builder’s policies. Request public liability, employers’ liability and relevant contract works documentation.
- Check your building contract. Establish who insures the existing structure, new works and materials.
- Discuss neighbouring properties. Check party wall responsibilities and any excavation-related insurance requirements.
- Confirm planning and building control arrangements. Planning permission and Building Regulations compliance are separate from insurance.
- Keep written records. Retain policy confirmations, certificates and relevant correspondence.
For complex construction contracts, ask a qualified insurance adviser and appropriate legal professional to review the insurance responsibilities before signing.
Do You Need to Update Home Insurance After the Extension Is Finished?
Yes. Once the extension is complete, tell your home insurance provider about the finished work and review your buildings and contents cover.
An extension can increase the property’s rebuilding cost, particularly when it adds rooms, structural elements or higher-value fixtures.
Remember that the rebuilding cost is different from the property’s market value.
You may also need to update the insurer about additional bedrooms, bathrooms, kitchens or changes in occupancy.
Keep completion certificates, relevant warranties and building documentation with your insurance records.
If your project includes a structural warranty, check what defects it covers and how long that protection lasts. A warranty is not the same as home insurance.
Planning a Home Improvement Project in London?
Property Eye Building Services (PEBS) provides building refurbishment, maintenance and home improvement services across London, including areas of Central, West and South London.
Our work covers property refurbishment, kitchens and bathrooms, plumbing, electrical services, joinery and decorating.
If your planned extension also involves refurbishing your existing living space, we can discuss the relevant aspects of your project and the work required.
Before proceeding with any structural extension, confirm the scope of construction services available and ensure your insurance arrangements have been reviewed by your provider.
Contact Property Eye Building Services to discuss your planned property improvements.
Disclaimer: This article provides general information about UK building and renovation insurance and is not personalised insurance or legal advice. Policy terms, exclusions and statutory obligations vary. Consult your insurer or a qualified insurance broker, and seek legal or surveying advice where appropriate, before beginning construction.